How to Use an FHA 203(k) for ADUs and Major Renovations
The FHA 203(k) does far more than cosmetic updates. Here's how it handles ADUs, mixed-use properties, contractor draws, and the real timeline to closing.
Real Estate Solutions That Fit Your Life. Guidance, strategy, and solutions wherever life takes you. Book a Call
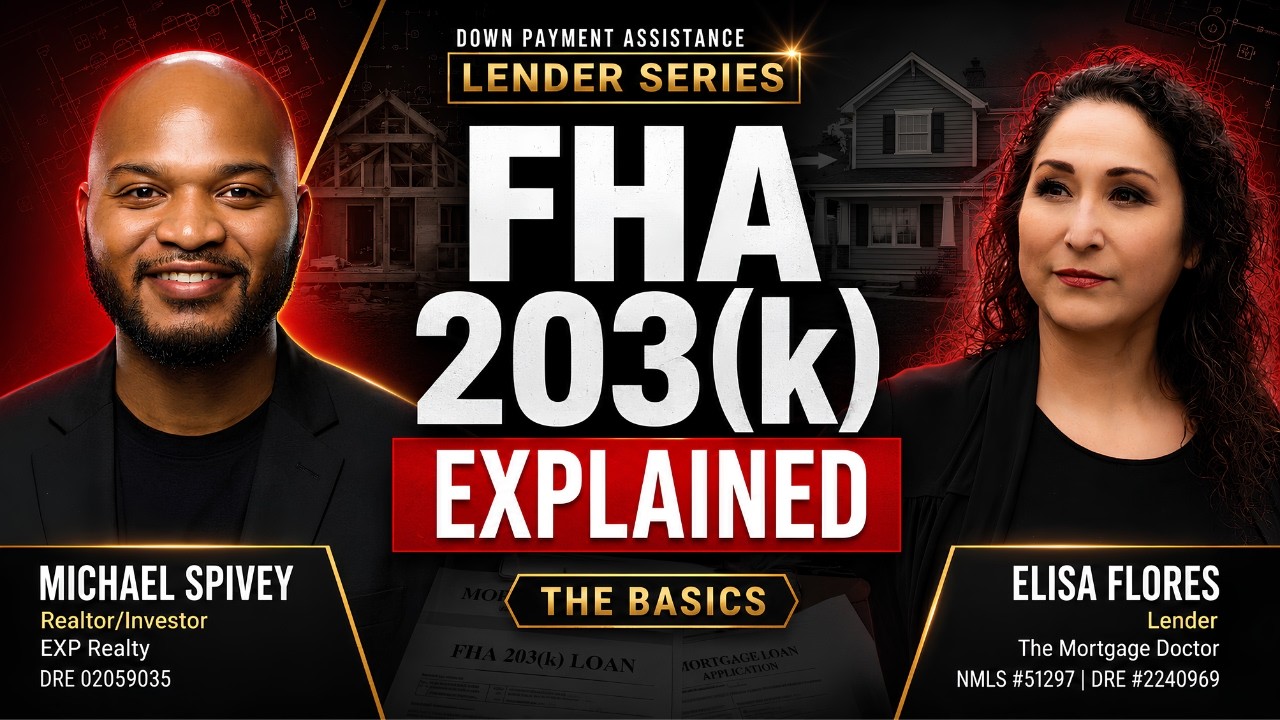
In the first part of our FHA 203(k) series, we covered how this loan combines a home purchase and renovation into a single FHA mortgage, and which property types qualify. This time, we’re digging into the more advanced side of the program, ADUs, mixed-use properties, financing payments during construction, and how these deals actually reach the closing table. We’re joined again by our trusted lending partner from American Pacific Mortgage to break it all down.
A quick refresher on how it works. An FHA 203(k) is a purchase loan and a renovation loan combined into one FHA mortgage, and you can also use it to renovate a property you already own. On a purchase, the buyer closes on the property first, then the renovation money goes into a controlled escrow account and is released as the work is completed. There are two versions: a Limited 203(k) for smaller, non-structural, mostly cosmetic projects, and a Standard 203(k) for major renovations, structural work, conversions, and additions. The Standard version generally requires at least $5,000 in eligible repairs and has no separate renovation dollar ceiling beyond FHA’s overall loan limits.
Can you add an ADU? Yes, potentially, and this is one of the most powerful parts of the Standard 203(k). It can finance far more than cosmetic updates. A buyer may be able to reconfigure a property, convert space, and add an accessory dwelling unit. Here in California, ADUs are hugely popular, and the appeal is obvious: adding one through the loan can create passive income for the homeowner down the road. One clarification worth noting, you generally can’t convert a single-family home into a duplex, but you can convert a single-family home to include an ADU, depending on eligibility with zoning and the parcel. Major structural construction points you toward the Standard 203(k).
What about mixed-use property? It can work. The key number to remember is 51%: a mixed-use property is eligible as long as at least 51% of the building’s square footage is residential, and the commercial use doesn’t create a health or safety concern. That health-and-safety standard is central to FHA, and you’ll see the same principle across most government loan programs. So yes, mixed-use is possible, but 51% residential is the threshold to keep in mind.
Financing your mortgage payments during renovation. Here’s a feature a lot of buyers don’t know about. With a Standard 203(k), if the property is uninhabitable during the renovation, your mortgage payments can be financed into the project, up to 12 months. FHA built this program to encourage homeownership, and that philosophy still holds: they want to make sure you can afford the home and actually live in it. So if you can’t live in it during construction, there’s a mechanism to wrap those payments in while you stay somewhere else until the work is done.
That said, there’s an important catch. You still have to qualify for that larger amount. Wrapping in a year of payments adds to your total loan, so you must qualify on the resulting mortgage. The reserve is tied to whether the property can be safely occupied, and for a 2-to-4-unit property, the lender, consultant, and appraiser have to evaluate whether a reserve is even warranted, so it’s never something to assume before reviewing the specific project. And once the approved reserve period ends, you’re responsible for making those payments yourself. Remember, too, that this comes with additional costs like the HUD consultant and reserves, which you’ll want to factor into your budget.
How the appraisal and “after-improved” value work. This is a big one to understand. You’re not just qualifying for the purchase price with an escrow attached. You qualify for the final FHA mortgage after the renovation costs and eligible project expenses are added in, things like labor and materials, permits, architectural or engineering fees, consultant fees, inspections, title updates, and a contingency reserve. That contingency reserve is one people forget, and it matters: as our lender put it, even a weekend handyman knows one trip to the hardware store somehow becomes three or four. On a real renovation, materials go up in price and timelines slip, and the contingency reserve is what protects you when they do.
Here’s the important distinction: buying a $450,000 home that needs $100,000 in work does not automatically mean a $550,000 loan. FHA applies a maximum mortgage calculation based on the required down payment, the appraisal results, eligible fees, and the county loan limit. It doesn’t necessarily make qualifying harder, the credit standards are still standard FHA underwriting. What can make it tougher is simply the larger final payment. That’s exactly why we work to determine your maximum all-in project budget before you start shopping. Otherwise, you risk falling in love with a house you can afford, but a renovation you can’t.
How contractors get paid. This is where buyers and contractors both need to understand the rhythm of the program. The renovation money is never handed to the borrower at closing, it goes into a rehabilitation escrow account and is released through controlled draws as the work is completed, stage by stage. Say you’re doing $40,000 of work: windows, flooring, siding, and a small bathroom remodel. The contractor completes the first agreed stage, it gets inspected, a draw request is submitted, and the lender releases those funds. Then the next stage, and the next.
That structure carries a clear warning for contractors: this is not a cash-up-front remodeling job. A contractor needs adequate working capital and has to be comfortable with the inspections, documentation, draw timing, permits, and oversight. And if something unexpected turns up, the contractor can’t just do the extra work and send a bigger bill, the change has to be documented and approved, because it’s a loan. That’s another reason the contingency reserve matters. Finally, choose your contractor based on documentation and financial capacity, not because “he’s a relative who owns a ladder.” They must be licensed and bonded, and, importantly, the contractor cannot be the homeowner. Even friends who are contractors themselves can’t act as their own contractor on their own 203(k). There’s a full approval process, and the contractor also works alongside the appraiser, who values the property as-is today and notes the scope of work to establish the after-completion value.
What’s the timeline? This isn’t a normal loan, so plan accordingly. A minimum of 45 days to close is the realistic target, with 45 to 60 days being typical. It takes longer than a standard FHA loan because there are more people in the mix, contractors have to be booked and provide bids, and underwriting has to review the permits, plans, and bids alongside the property and the borrower. A clean walkthrough looks like this: get pre-approved based on an approximate all-in budget, find a property, confirm enough time in the contract, have the contractor bid the work (and a HUD consultant get involved on a Standard loan), then appraisal and underwriting happen together. At closing, the seller receives the purchase funds and the renovation money goes into escrow. Work begins after closing, once permits are in place, with inspections and draws after each stage, and a final inspection to close out the renovation account. The rehab period itself can run 6 to 12 months on a Standard 203(k), especially in California where some cities and counties have slower permitting; smaller Limited projects can wrap up faster.
So why don’t more people use this program? The loan itself isn’t the problem, it’s that it needs an experienced team, and many people find it daunting. A traditional loan evaluates a house largely as it is. A 203(k) asks everyone to evaluate what the property will become. But that’s exactly where the opportunity lives. In a market where move-in-ready homes attract the most competition, a 203(k) lets you look at inventory everyone else is ignoring, a home that’s been sitting on the market for months, where the seller may be very open to negotiating on price or credits. It’s often a win for everyone: you get the property you really want, and the seller gets their home sold.
If you’re considering a property that needs renovation, whether it’s a single-family home, a multi-family property, or another opportunity, the most important step is understanding your financing before you start making offers. If you have questions about the FHA 203(k) or want to explore which financing programs make sense for your specific situation, reach out to our team, we’d be happy to help you figure out your next step. Call or text us at 510-500-5428, email us at info@spiveydaniel.com, or visit spiveydanielrealestategroup.com.
-
Real Estate Solutions That Fit Your Life. Guidance, strategy, and solutions wherever life takes you. Book a Call
-
Free Home Valuation. Don’t trust a Zestimate. Get a personalized home valuation directly from a Spivey & Daniel real estate expert. Get Estimate
-
Free Newsletter. Get our latest Q&A, insights, and market updates to make smarter decisions. Subscribe Now